
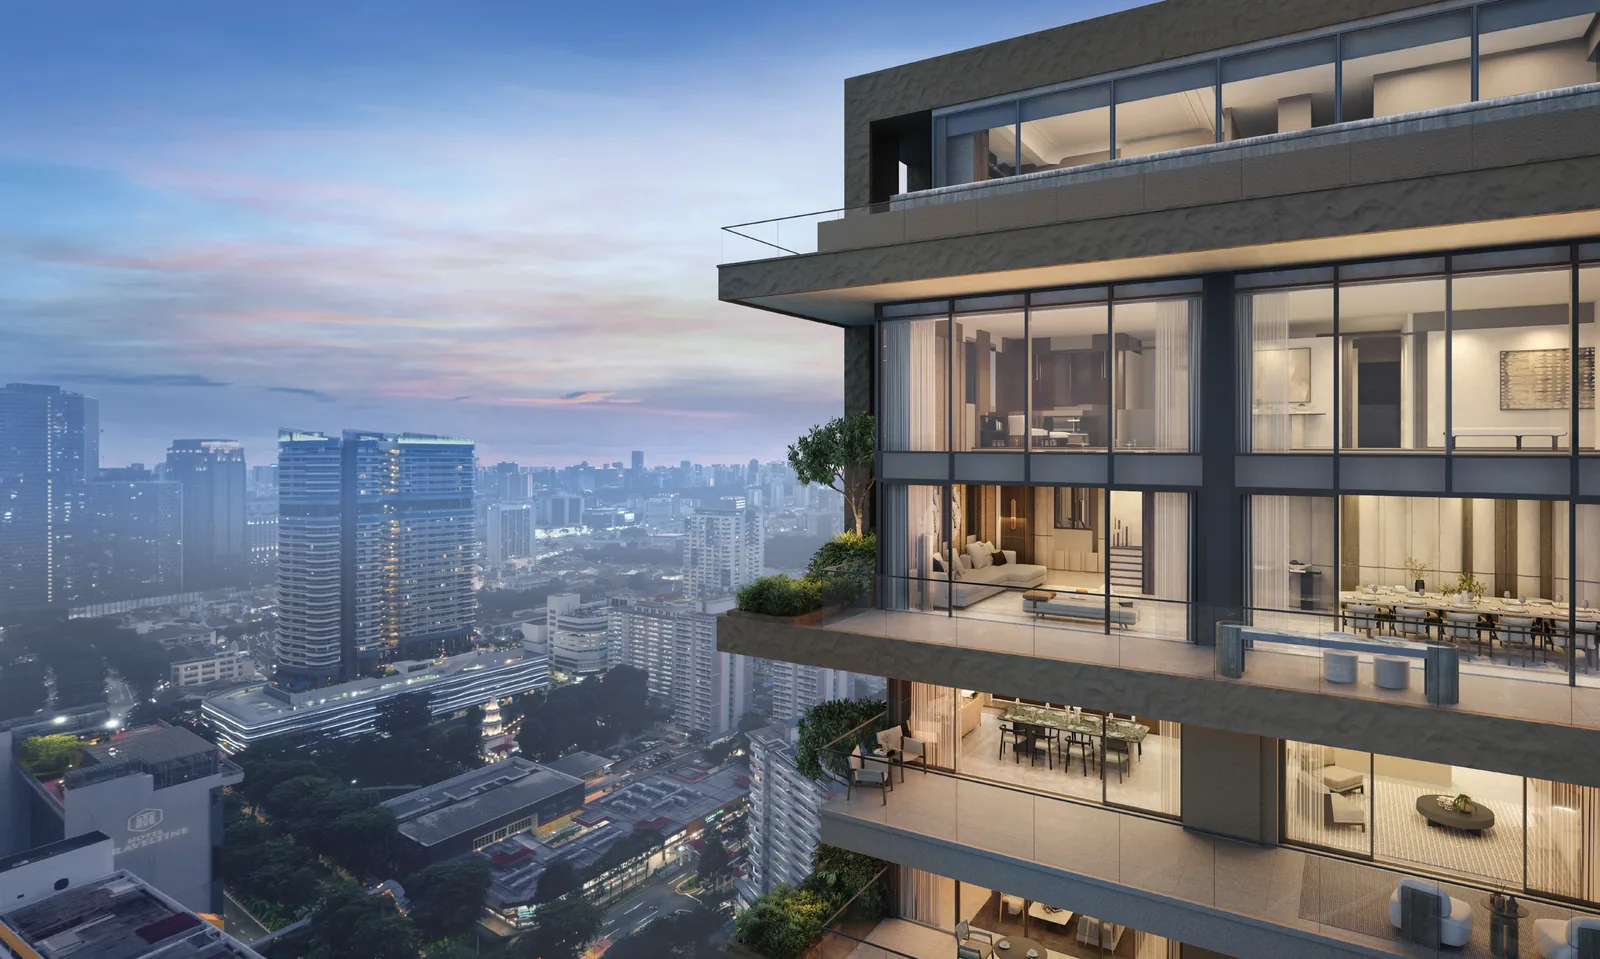
Homes at Aurea are sold on the normal progressive payment scheme for a building under construction: the price is paid in instalments that follow the tower as it rises, from the booking fee to the final payment at statutory completion.
Aurea Progressive Payment Stages
The Housing Developers Rules prescribe the stages and percentages. The right-hand column shows the running total.
| Stage | % of price | Cumulative |
|---|---|---|
| Booking fee, on grant of the option to purchase | 5% | 5% |
| Sale and purchase agreement, within 8 weeks | 15% | 20% |
| Completion of foundation | 10% | 30% |
| Completion of reinforced concrete framework | 10% | 40% |
| Completion of partition walls | 5% | 45% |
| Completion of roofing and ceiling | 5% | 50% |
| Completion of doors, windows, electrical wiring and plumbing | 5% | 55% |
| Completion of car park, roads and drains | 5% | 60% |
| Temporary Occupation Permit (TOP) | 25% | 85% |
| Certificate of Statutory Completion | 15% | 100% |
Standard schedule for a building under construction under the Housing Developers Rules, checked 7 October 2026. The sale and purchase agreement governs; the Sales Concierge confirms the stages already certified at the time of booking.
Aurea Cash, CPF and Loan Portions
The 5% booking fee is paid in cash. The part of the price the bank does not lend is paid next, before any loan is drawn, and MAS sets how much of it must be cash. A buyer with no housing loan outstanding may borrow up to 75%: of the 25% paid first, at least 5% is cash, which the booking fee covers, and the remaining 20% may come from cash or CPF Ordinary Account savings within CPF rules.
| Borrower | Max loan | Own funds | Minimum cash |
|---|---|---|---|
| No outstanding housing loan | 75% | 25% | 5% |
| No outstanding loan, tenure over 30 years or past age 65 | 55% | 45% | 10% |
| One outstanding housing loan | 45% | 55% | 25% |
| Two or more outstanding housing loans | 35% | 65% | 25% |
Source: MAS, checked 7 October 2026. Limits can change; confirm with MAS or a bank before signing.
At 75% financing, the booking fee and the 15% on signing take the buyer to 20%; half of the foundation instalment completes the 25%, and from then on the bank pays each certified stage. The Aurea housing loan page explains when the lower limits apply.
How an Aurea Loan Is Drawn
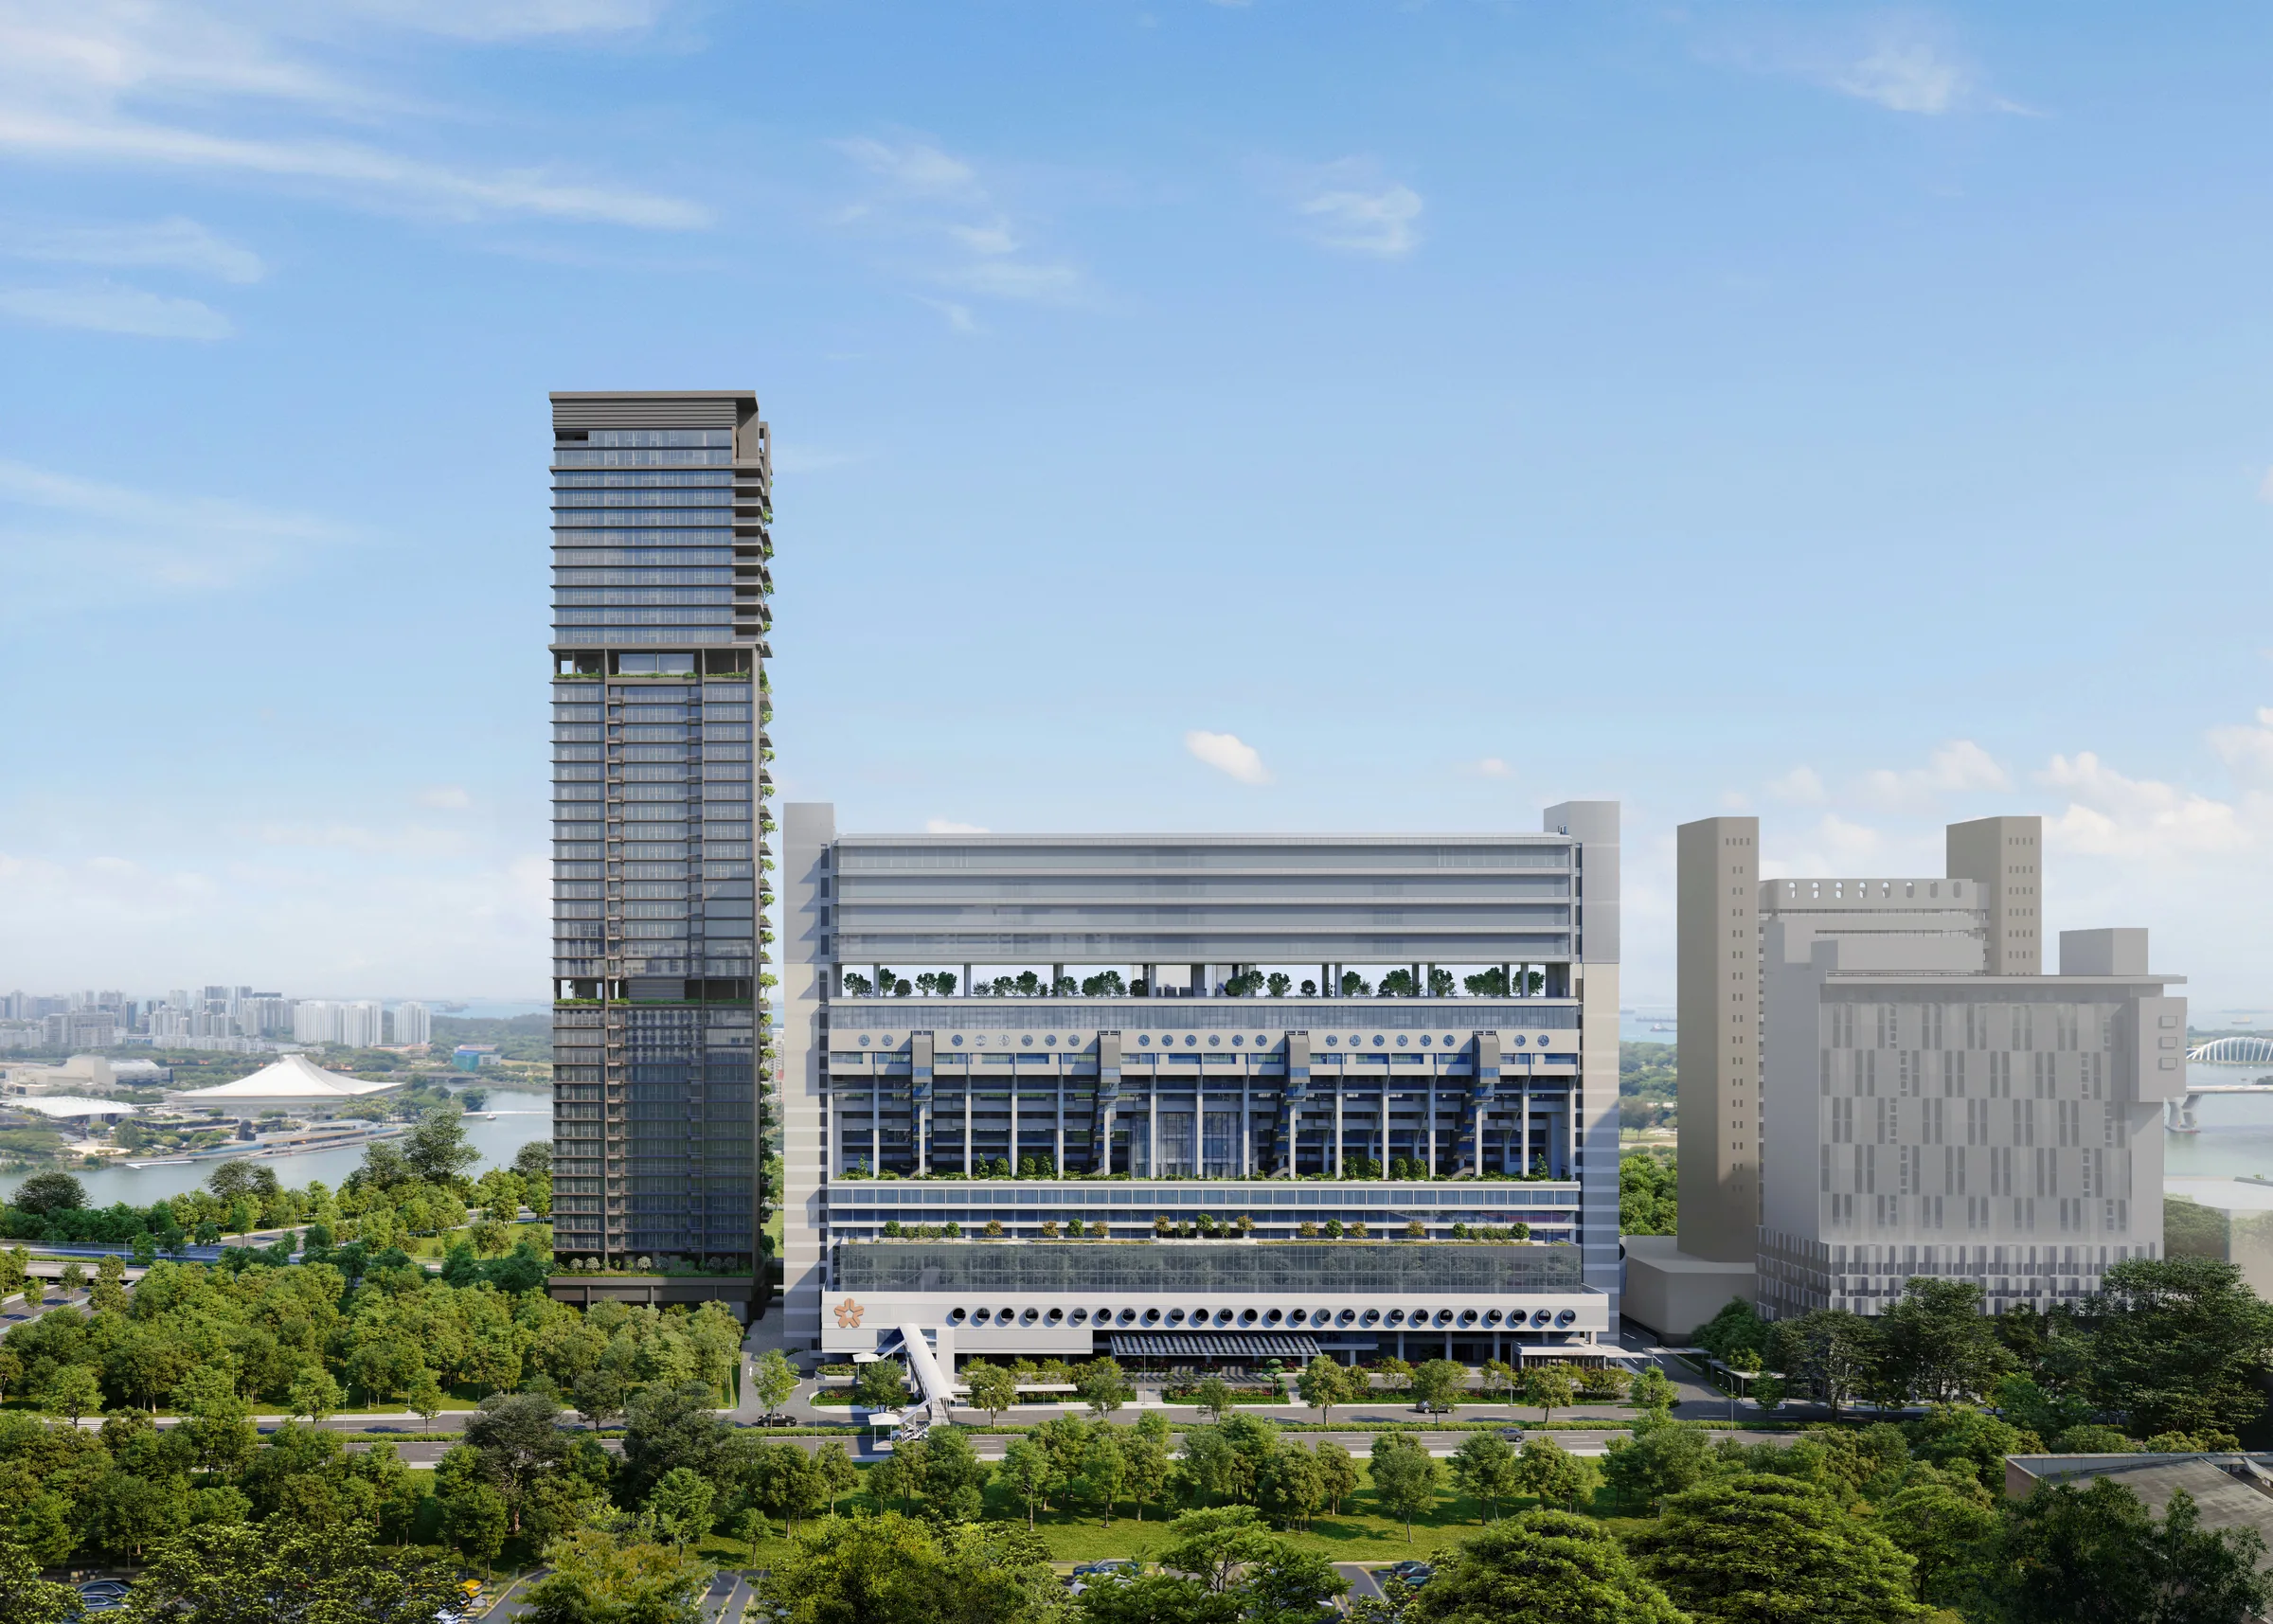
When a stage is certified, the developer issues a notice and the bank releases that instalment. Interest during construction is charged only on the amount drawn, so repayments start small and grow as the 45-storey tower is completed.
Where early stages are already certified when a home is booked, those instalments fall due on the timetable in the sale and purchase agreement. The Sales Concierge confirms which stages have been reached.
Aurea Completion Dates and the Final Instalments
The developer states an expected vacant possession date of 31 March 2030 and an expected legal completion date of 31 March 2033. The 25% instalment falls due on TOP, and the final 15% on the Certificate of Statutory Completion.
Stamp duty is paid separately and early, as the Aurea stamp duty page sets out. The progressive payment calculator gives the amount and the estimated monthly instalment at every stage for a chosen price and loan.
Register Your Interest in Aurea
The Aurea e-brochure is ready to download in English and Chinese. The Sales Concierge sends the floor plans and the current price list for Aurea, and arranges a private viewing of the show units at a time that suits you.
What the Sales Concierge sends
- The full project details, alongside the e-brochure you can download now.
- The floor plans of the Prestige and Signature Collections, from the 635 sq ft 2-bedroom to the 1,798 sq ft 4-bedroom Premium.
- The current price list and the balance units chart by stack and level.
- A private showflat appointment and the facility plans for the three landscaped levels.
Register Your Interest
No obligation. The Sales Concierge responds personally to every enquiry.
To talk it through instead, call +65 6200 6220 or send a WhatsApp message to the same number.