
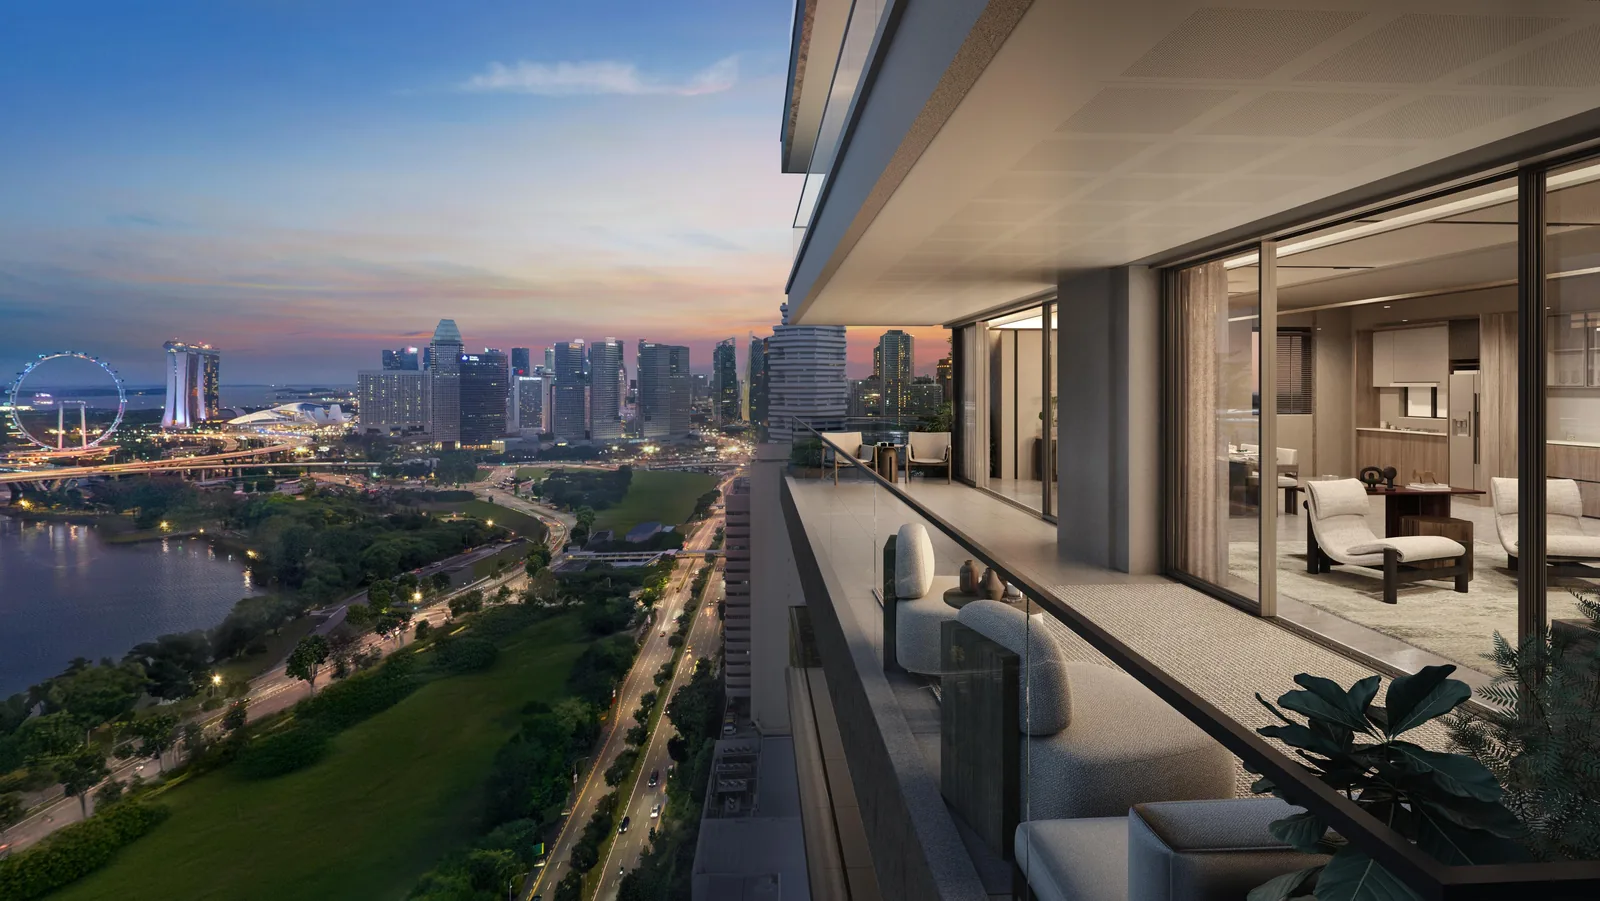
Two MAS rules size the loan on an Aurea home: the loan-to-value (LTV) limit, which caps the loan against the price, and the Total Debt Servicing Ratio (TDSR), which caps all monthly debt repayments against income. The figures below were in force on 7 October 2026.
Aurea Loan-to-Value Limits
The limit depends on how many housing loans the borrower already has, and each tier has a standard figure, a lower figure and a minimum share of the price paid in cash.
| Outstanding housing loans | Standard LTV | Lower LTV | Minimum cash |
|---|---|---|---|
| None | 75% | 55% | 5% (10% in the lower band) |
| One | 45% | 25% | 25% |
| Two or more | 35% | 15% | 25% |
Source: MAS, checked 7 October 2026. Limits can change; confirm with MAS or a bank before signing.
When the Lower Band Applies at Aurea
A loan falls into the lower band if either of these is true:
- the tenure is longer than 30 years; or
- the loan would run past the borrower’s 65th birthday, using the income-weighted average age for joint borrowers.
For example, a 31-year-old taking a 34-year loan finishes at 65 but exceeds 30 years of tenure, so the lower band applies; a 45-year-old on a 25-year loan stays within 30 years but finishes at 70, so it applies too. Loans on private property run for at most 35 years.
The TDSR Test for Aurea Buyers
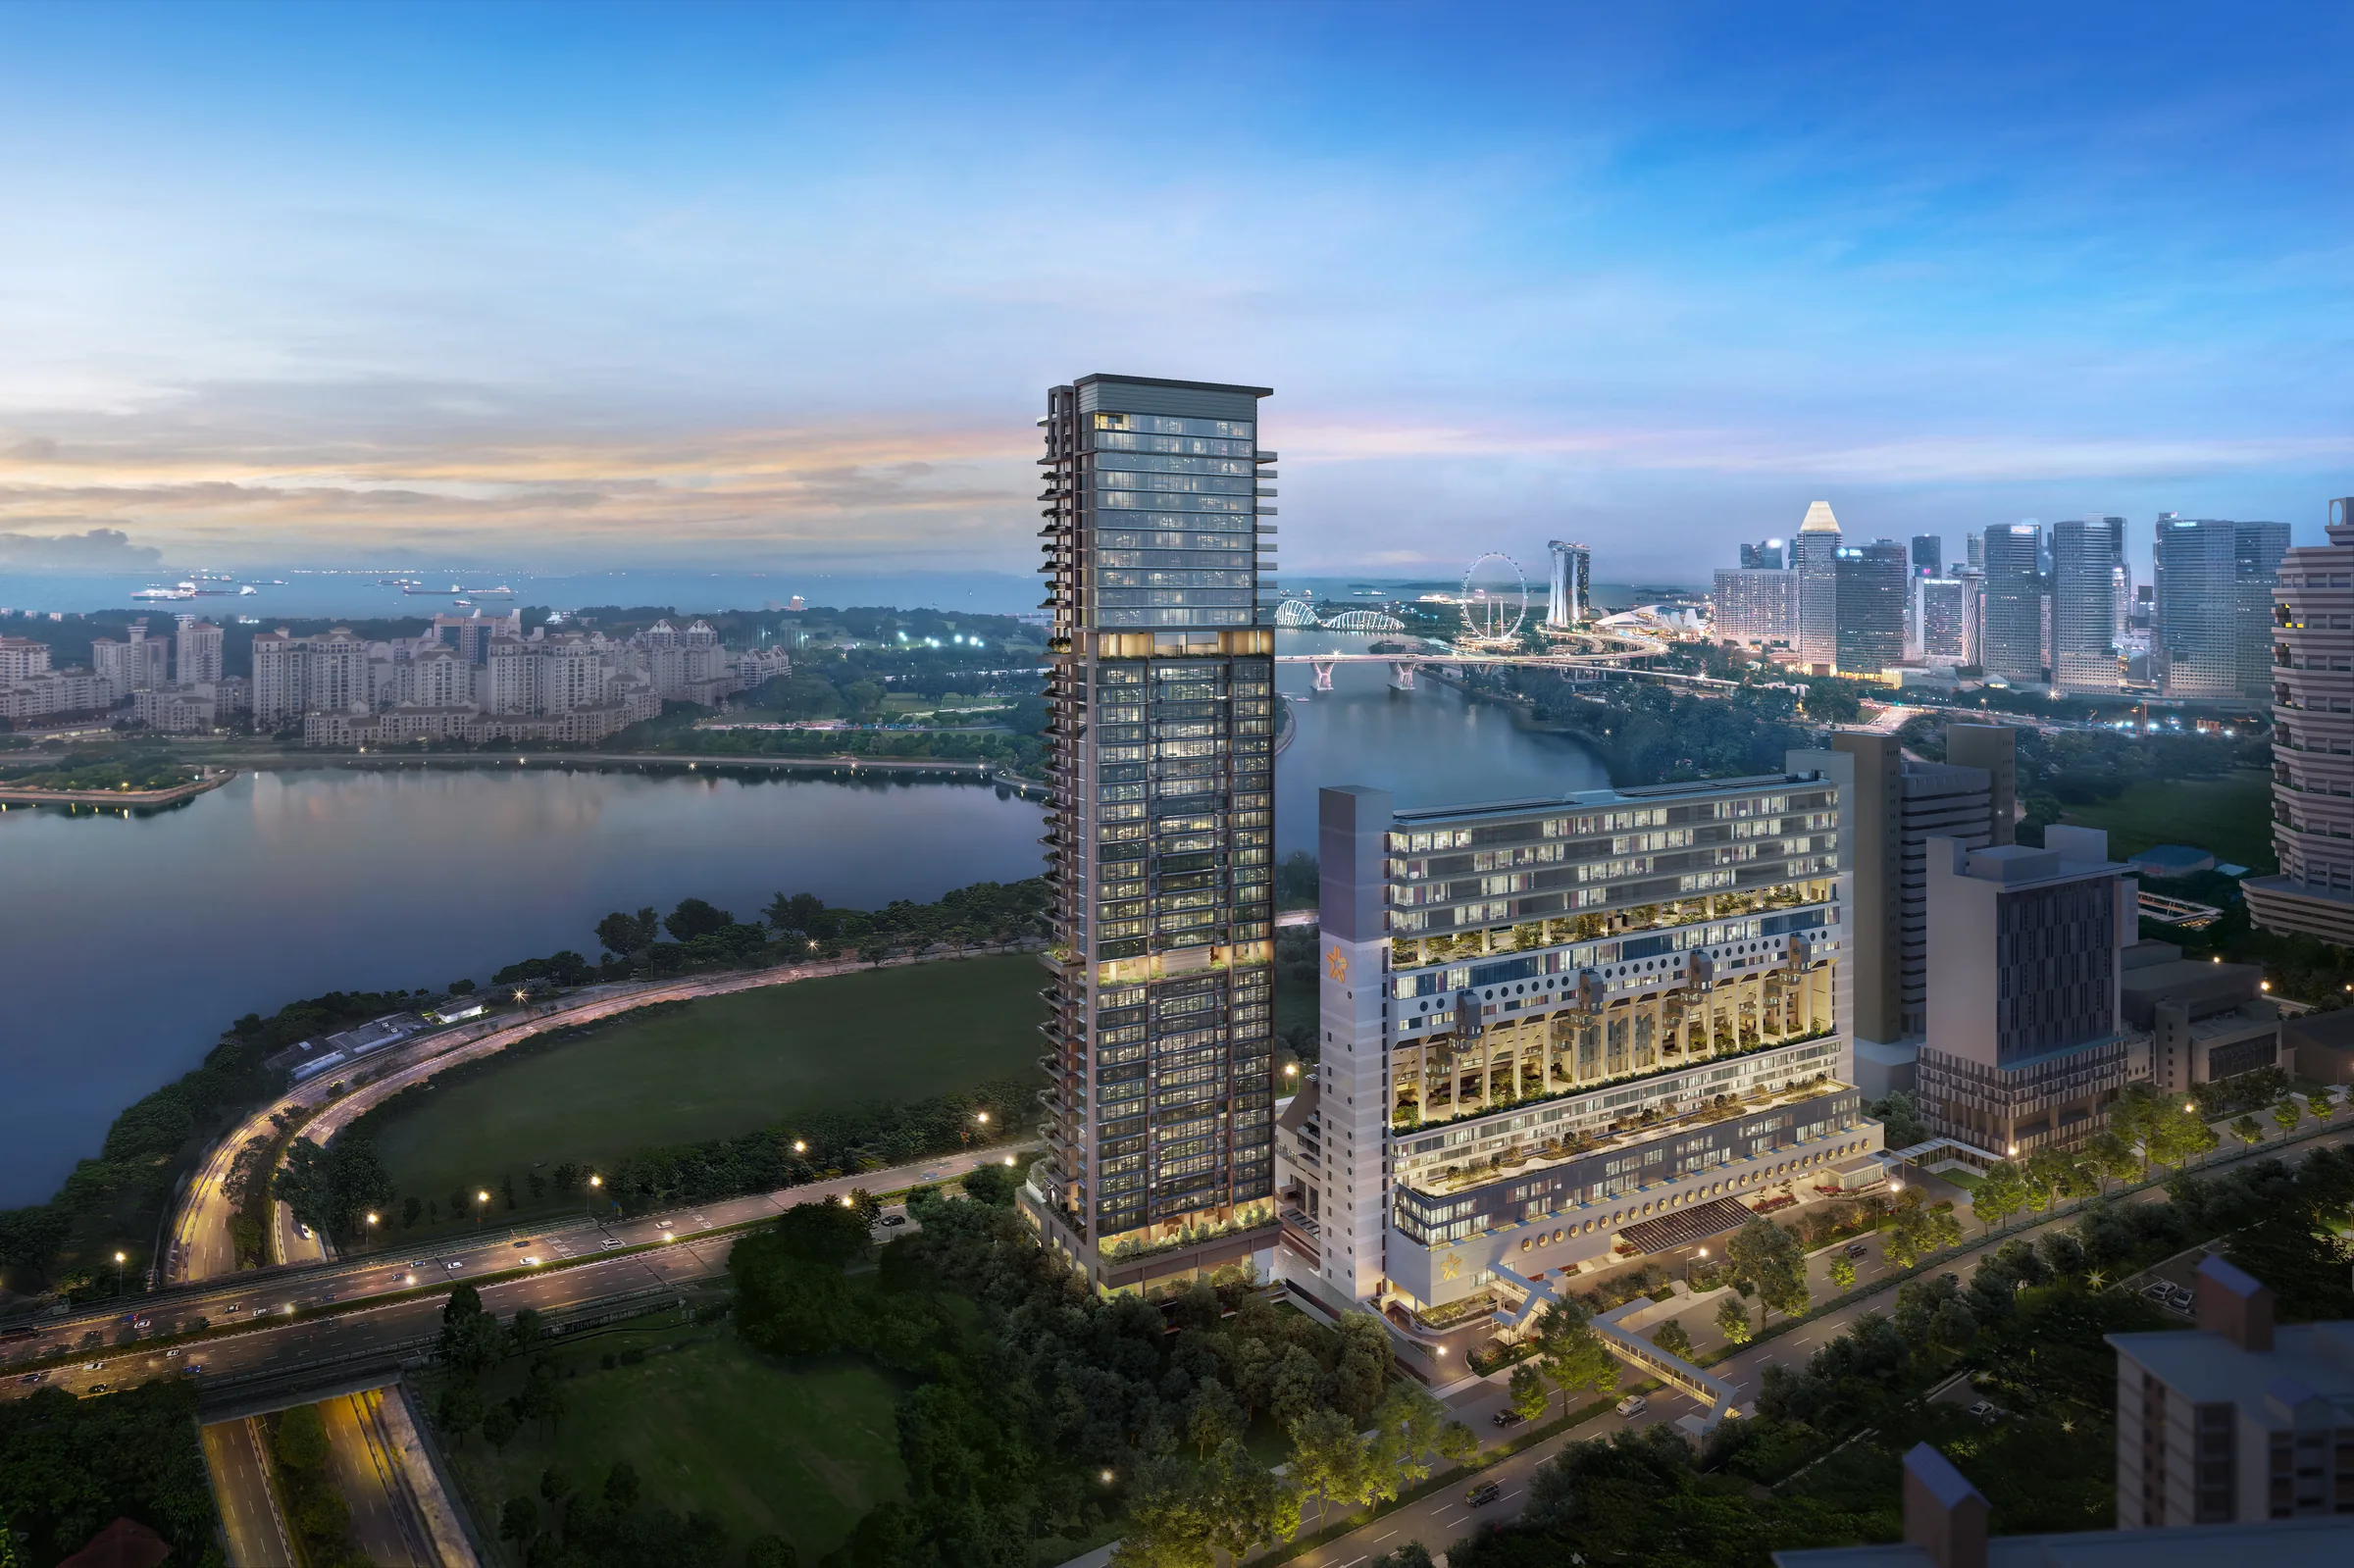
All monthly debt repayments, including the new loan, must stay within 55% of gross monthly income. The new loan is tested at a medium-term interest rate rather than the rate a bank offers, which leaves room for rates to rise.
| Rule | As at October 2026 |
|---|---|
| TDSR limit | 55% of gross monthly income |
| Interest rate used for the test | 4%, or the loan’s own rate if higher |
| Variable and rental income | Counted at 70%, after a 30% haircut |
| Longest tenure, private property | 35 years |
| Joint borrowers | Income-weighted average age |
Source: MAS, checked 7 October 2026. Limits can change; confirm with MAS or a bank before signing.
Fixed salary counts in full. Credit card minimum payments, car loans and other property loans are deducted before the remaining capacity is turned into a loan amount. The Aurea TDSR calculator applies these rules for one or two borrowers.
In-Principle Approval for an Aurea Purchase
Many buyers obtain a bank’s in-principle approval before booking. It states the amount the bank is prepared to lend on the details given, subject to final approval and valuation, and gives a firm figure for planning the stamp duty, the booking fee and the cash portion. Each bank sets its own terms and validity period.
Once the buyer’s own portion is paid, the loan is drawn stage by stage under the Aurea payment scheme, and the progressive payment calculator shows the split at each stage.
Register Your Interest in Aurea
The Aurea e-brochure is ready to download in English and Chinese. The Sales Concierge sends the floor plans and the current price list for Aurea, and arranges a private viewing of the show units at a time that suits you.
What the Sales Concierge sends
- The full project details, alongside the e-brochure you can download now.
- The floor plans of the Prestige and Signature Collections, from the 635 sq ft 2-bedroom to the 1,798 sq ft 4-bedroom Premium.
- The current price list and the balance units chart by stack and level.
- A private showflat appointment and the facility plans for the three landscaped levels.
Register Your Interest
No obligation. The Sales Concierge responds personally to every enquiry.
To talk it through instead, call +65 6200 6220 or send a WhatsApp message to the same number.